When you hold a highly appreciated stock, business interest, or real estate asset, selling can create a significant tax bill. Traditional tax-loss harvesting lets you sell underperforming investments to reduce your tax liability, but has its limits. For those with enough assets, tax-aware long/short strategies can be a boon for those with significant capital gains and a commensurate tax bill.
What Is a Tax-Aware Long/Short Strategy?
A long-short strategy combines:
- Long positions in stocks the manager believes will appreciate.
- Short positions in stocks the manager believes may decline.
Traditional Tax-Loss Harvesting
Long-Only Extension
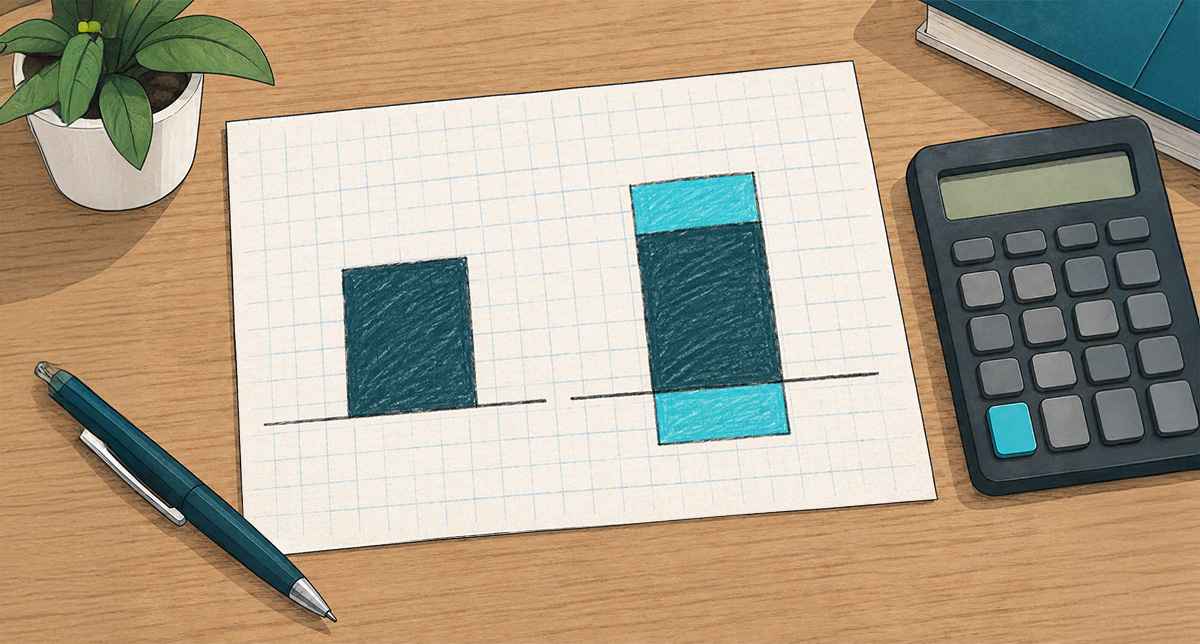
Passive long-only approaches may start out generating tax benefits, but after a few years, the strategy may rely on market dips to generate further benefits. Tracking error may also rise over time as losses are harvested.
Long/Short Tax-Loss Harvesting
Adding a Modest Long/Short Extension
A long/short extension may help increase the magnitude of tax benefit generation and may help generate benefits in both rising and falling market environments. Extensions may also be helpful in managing tracking error.
Because these strategies typically involve more active trading than traditional portfolios, they may create opportunities to realize losses that can potentially offset gains elsewhere in a taxable portfolio.
What type of investors or business owners can benefit from such a strategy?
Managing Concentrated Positions
Investors seeking to diversify or selling a highly appreciated investment (such as company stock) may use realized losses from a long/short strategy to help offset capital gains generated during diversification.
Offsetting Other Major Gains
Long-short strategies are sometimes used alongside taxable events such as:
- Business sales
- Real estate transactions
- Stock option exercises
- Portfolio rebalancing
The objective is generally not to eliminate taxes, but to manage the timing and impact of taxable gains.
How Long Have These Strategies Been Around?
Long/short strategies have been around for decades. Famed investor Alfred Winslow Jones is often credited with being one of the first investors to employ this strategy way back in 1949. Quant investment managers popularized these strategies in the 1970s and 1980s using data-driven, statistical models to select stocks and they became popular with institutional and very high-net-worth investors. It is only in the last few years, since advances in portfolio management and personal indexing, that such strategies have become accessible to investors who have at least $1 million to invest in them.
Important Considerations
Manager Selection Matters
Results depend heavily on the manager’s ability to identify attractive long and short opportunities. Poor execution can outweigh any potential tax benefit.
Short-selling Risk
Short-selling involves borrowing a stock, selling it, and buying it back later a lower cost, thereby profiting from the difference. By itself, the strategy is risky because there is technically no limit in how high the stock can rise and therefore your risk of loss is also technically unlimited. There are also borrowing costs to contend with.
Leverage Risk
These strategies use leverage through a combination of long and short positions, creating market exposure that exceeds invested capital. While this can create tax benefit and boost potential returns, it can also amplify losses and increase volatility.
Taxes Are Not Entirely Eliminated
Tax-aware long/short strategies are not a silver bullet. While realized losses may offset gains elsewhere, as other investments in the portfolio appreciate there will always be some unrealized gains. If the portfolio is later sold at a gain, taxes may become due.
Higher Costs
Management fees, financing costs, short-selling expenses, and trading costs are often higher than those of traditional equity strategies.
Regulatory Risk
Tax-aware long/short strategies rely in part on current tax laws and regulations to deliver their intended benefits. Changes in tax rules, the treatment of capital gains and losses, wash sale provisions, or other tax-related regulations could reduce the effectiveness of these strategies and diminish after-tax returns.
How Elevation Wealth Partners Evaluates These Strategies
When considering a long-short strategy, we focus on:
- Overall risk tolerance
- Tax situation
- Liquidity needs
- Long-term objectives
- Manager quality and track record
For the right investor, a long-short strategy can be a useful complement to a broader tax-aware wealth management plan, particularly when addressing concentrated holdings or significant liquidity events.
Industry Developments
Interest in tax-aware long/short strategies has grown in recent years. Notably, Charles Schwab recently increased the minimum asset requirement for certain tax-aware long-short separately managed accounts from $1 million to $10 million for new accounts.
Investors should evaluate these strategies based not only on potential tax benefits, but also on manager experience, investment process, risk profile, costs, tax implications, and platform availability.
Bottom Line
Long/short strategies can be a helpful tool for managing concentrated positions and offsetting taxable gains, but they come with additional complexity, costs, and risks. While the tax benefits can be meaningful in the right circumstances, these strategies should be viewed as part of a broader investment and tax-planning process rather than a standalone solution.
For investors facing concentrated stock positions, business-sale proceeds, real estate gains, or other significant taxable events, a carefully selected long-short strategy may provide flexibility that traditional long-only portfolios cannot. The key is ensuring the strategy aligns with your overall financial plan, risk tolerance, and long-term objectives.
If you’d like to explore whether this type of strategy fits your situation, we’d be happy to walk through it together and coordinate with your tax advisor as needed.
Sources: Quantinno, Schwab Center for Financial Research.
Disclosure: This article is for educational purposes only and does not constitute investment, tax, or legal advice. Long-short strategies involve risks, including market risk, leverage risk, short-sale risk, liquidity risk, and manager risk. Investors should consult their CPA, tax advisor, or attorney regarding their specific circumstances. All investments involve risk, including the possible loss of principal. Past performance is not indicative of future results. See additional disclosures.